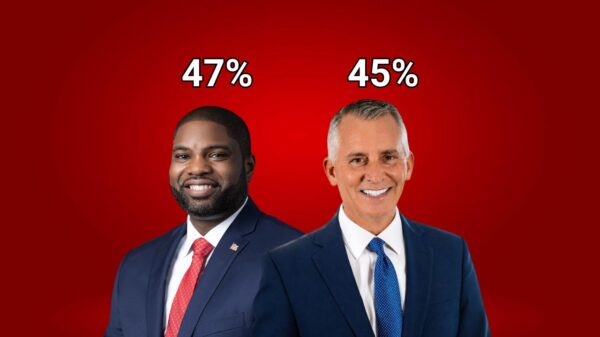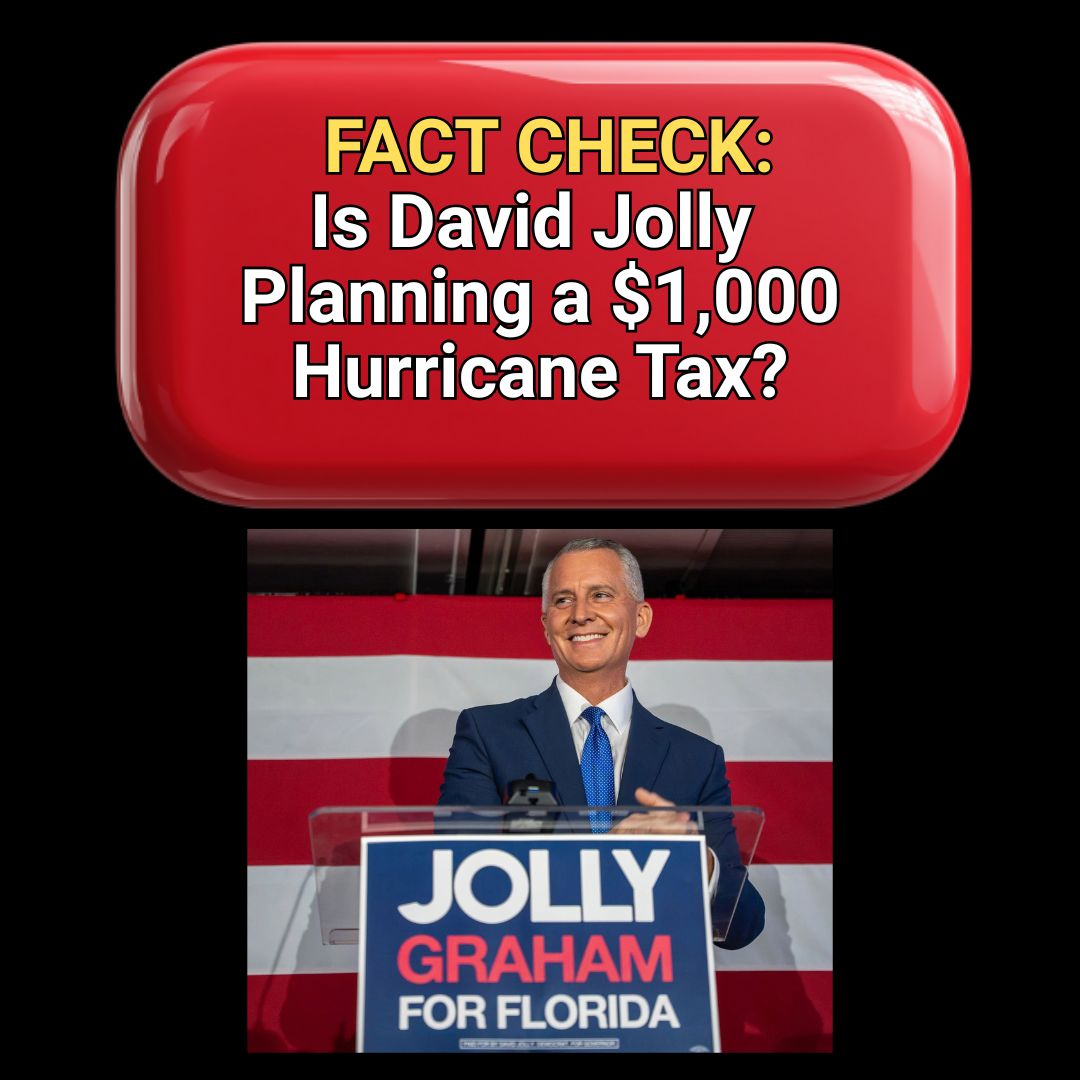
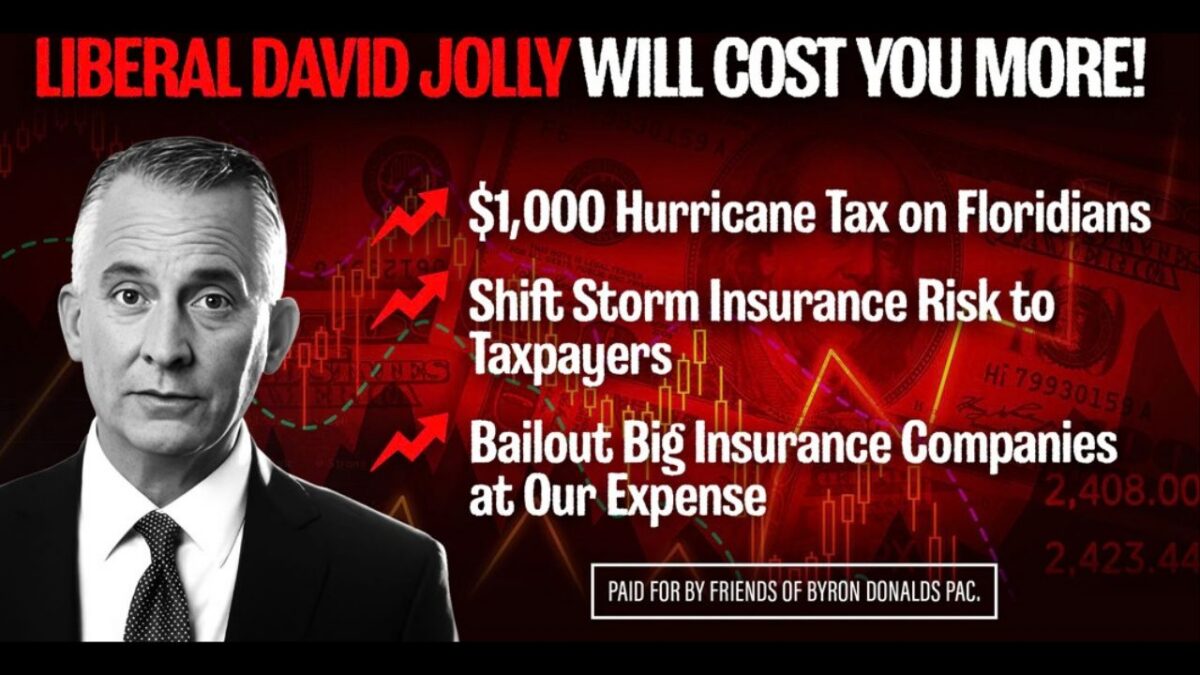
Republican gubernatorial candidate Byron Donalds has attacked Democratic opponent David Jolly’s homeowners insurance proposal by claiming it would result in a $1,000 “Hurricane tax” on Florida families every year.
Jolly’s published proposal, however, does not contain a $1,000 annual tax or assessment on homeowners.
The $1,000 figure comes from a separate study examining what could happen if Florida dramatically expanded the role of Citizens Property Insurance Corp. and placed residential wind coverage statewide under the government-backed insurer. The study did not specifically analyze Jolly’s proposal.
What Is Jolly Proposing?
Jolly has proposed creating an expanded state-backed fund responsible for hurricane and wind risk on Florida homes.
Private insurance companies would continue selling homeowners insurance but would no longer have to include hurricane and wind risk in their premiums.
Jolly’s campaign says the fund would first accumulate sufficient reserves and purchase reinsurance before beginning coverage. His campaign has suggested several possible funding sources, including additional insurance-company tax revenue, a fee on real estate transactions and existing tourist-tax revenue.

The Florida Legislature would ultimately have to establish the funding mechanism.
Jolly’s campaign says there would be no annual $1,000 homeowner assessment under its proposal.
Could Floridians Still Face an Assessment?
That question depends on how lawmakers would write the legislation.


Florida already operates the Florida Hurricane Catastrophe Fund, which serves as a form of reinsurance for private property insurers.
Under existing Florida law, the fund has authority to impose emergency assessments if its revenues are insufficient to meet its financial obligations.
Florida Statute 215.555 allows the State Board of Administration to direct the Office of Insurance Regulation to impose an emergency assessment on most property and casualty insurance premiums in Florida.
The assessment can apply to insurance policies beyond homeowners coverage, including automobile and other property-and-casualty policies. Workers’ compensation and medical malpractice insurance are among the exclusions.
Citizens Property Insurance also has an assessment mechanism.
If Citizens suffers a major deficit, its own policyholders can first face a surcharge of as much as 15% of their premium. If a deficit remains, an emergency assessment of as much as 10% annually can be applied to assessable insurance premiums statewide, including policies issued by private insurers.
For example, a household paying a combined $8,000 annually for homeowners, automobile, and other assessable insurance could theoretically face hundreds of dollars in additional charges if a large emergency assessment were imposed.
The actual amount would depend on the assessment percentage and the household’s insurance premiums.
Would Those Existing Rules Apply to Jolly’s Plan?
Not necessarily. Jolly has said his proposal would require changes to existing law. His campaign says the new fund would be adequately capitalized and backed by reinsurance before assuming hurricane risk.
Because legislation creating the expanded fund has not been enacted, lawmakers could determine what assessment authority — if any — the fund would have after catastrophic losses.
That means the existing Citizens assessment system cannot automatically be applied to Jolly’s proposal.
At the same time, Florida law demonstrates that statewide emergency insurance assessments are already an available financing mechanism for state-backed insurance programs. Whether similar assessments would remain available under Jolly’s expanded catastrophe fund would depend on the legislation ultimately approved by lawmakers.
BYRON DONALDS’ ATTACK AD IS THE ORIGIN OF THE $1,000 HURRICANE TAX
What Floridians Should Know About the $1,000 Claim
Three distinctions are important:
The $1,000 figure comes from a catastrophic-loss scenario involving an expansion of Citizens Property Insurance, not from a provision contained in Jolly’s insurance proposal.
The study did not conclude that Florida families would automatically pay $1,000 every year.
Florida currently allows state-backed insurance entities to impose assessments on policyholders following severe financial losses, and lawmakers could authorize some type of assessment when designing Jolly’s proposed fund.
The ultimate financial risk to taxpayers and insurance customers therefore would depend on several factors that have not yet been determined, including the fund’s reserves, reinsurance protection, hurricane losses and the financing provisions adopted by the Florida Legislature.